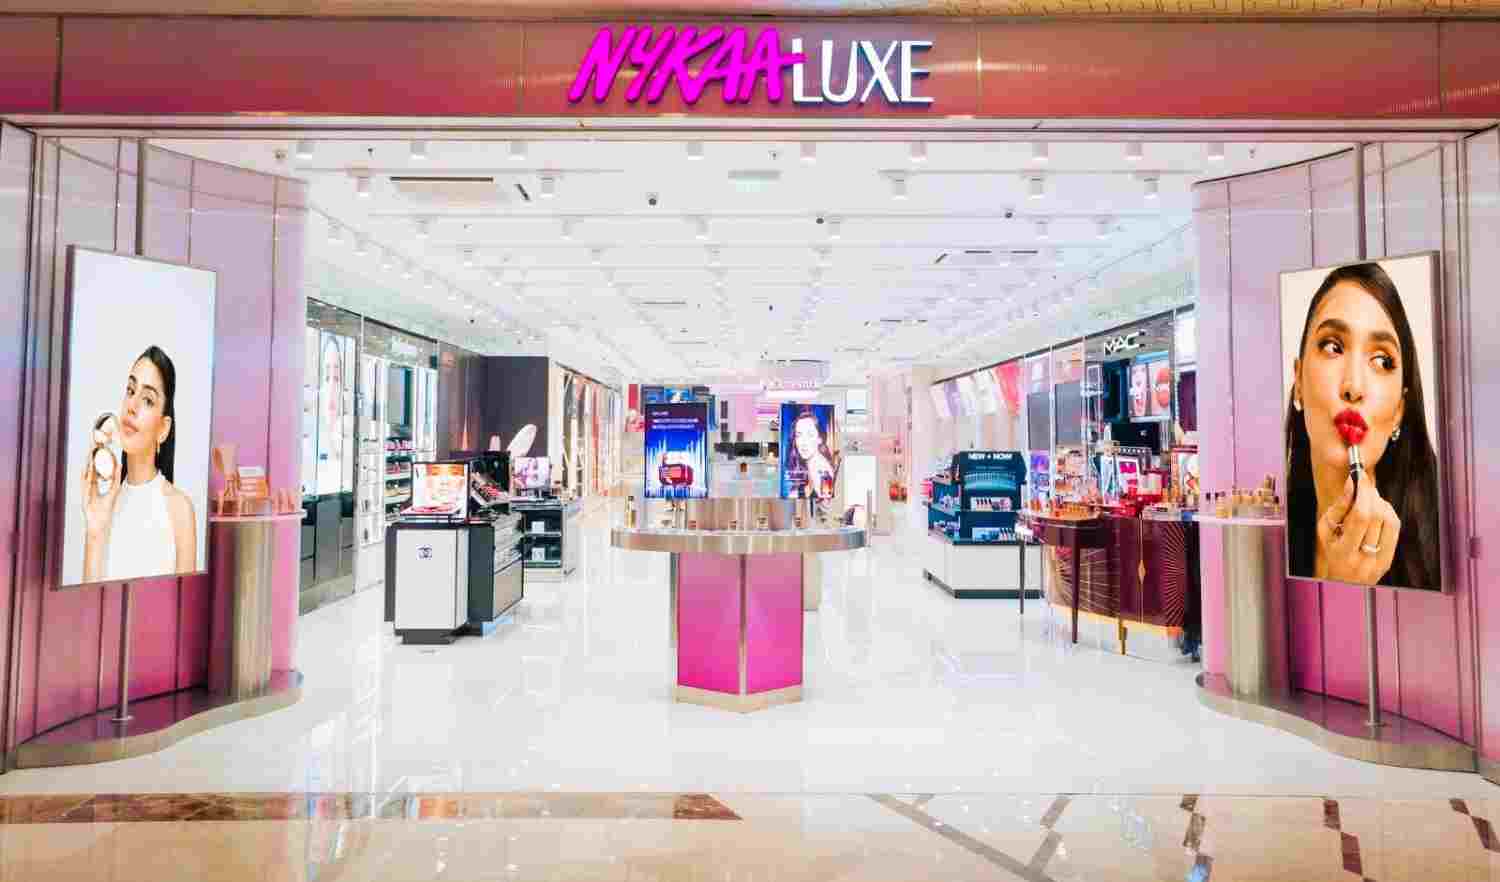
Nykaa’s parent FSN E-Commerce Ventures delivered a set of numbers on 4 November 2026 that look impressive on paper and still leave a bitter aftertaste. Consolidated net profit more than tripled to ₹101.2 crore from roughly ₹33-34 crore a year earlier. Operating revenue climbed 28.1 percent to ₹3,006 crore. EBITDA rose 65.6 percent to ₹263 crore and the margin expanded to 8.7 percent from the 6.7-6.8 percent range. Beauty revenue hit ₹2,699.7 crore, up 26.6 percent, with segment profit before exceptional items jumping to ₹180.2 crore. Fashion losses narrowed. The board also cleared an 82 percent stake buy in premium makeup brand Simply Nam for up to ₹33 crore.
These are real gains. The company is scaling, controlling costs better than revenue is growing, and converting more of the beauty business into actual profit. Sequential numbers also improved—profit up nearly 27 percent and revenue up 8 percent from the June quarter. On the surface this is the story of a private-sector platform that figured out product mix, store expansion (338 outlets), brand additions and omnichannel execution.
Look closer and the picture is less flattering for the country that is supposed to be powering this growth. The same households buying lipstick, skincare and apparel are living with elevated food and fuel costs, sticky urban inflation, and a tax system that still treats formal retail and digital platforms as cash cows rather than growth engines. Every percentage point of margin expansion at Nykaa is being earned against a backdrop of policy that has failed to deliver affordable credit, predictable GST rates on beauty and fashion categories, or logistics infrastructure that does not extract a silent tax on every order.
The government loves to claim credit for rising formalisation and digital commerce. Yet the regulatory thicket around inventory, data, advertising claims and foreign brand partnerships remains thick enough to slow smaller players and raise compliance costs for everyone. When a listed company can post 28 percent growth and still need to acquire niche brands to stay competitive, it is less a sign of booming domestic entrepreneurship and more a reflection of how difficult it remains to scale pure-play Indian brands without deep capital and political patience. The middle class is paying higher prices for the same products because the system has not fixed the cost of capital, the cost of compliance, or the cost of moving goods across state borders efficiently.
Nykaa’s fashion vertical is growing faster than beauty in percentage terms, yet the absolute contribution remains smaller and the path to consistent profitability is still being negotiated. That is not a company failure alone; it is the predictable outcome of an economy where discretionary spending is uneven, employment quality is weak, and real wage growth for large sections of urban India has been muted. When consumers stretch to buy premium beauty but delay apparel or trade down, the platform can still report strong overall numbers while the underlying demand is more fragile than the headlines suggest.
The acquisition of Simply Nam is rational portfolio expansion. It is also a quiet admission that organic brand building under current conditions is slower and more expensive than buying ready platforms. Capital is flowing to the winners who already have scale, while the broader retail and consumer ecosystem continues to struggle with high working-capital needs and policy uncertainty.
Investors will celebrate the margin expansion and the threefold profit jump. They should also notice that the same government that talks endlessly about ease of doing business has left the cost structure of Indian consumption still unnecessarily high. Nykaa has executed. The system around it has not. Until policy stops extracting more from formal platforms and households than it returns in infrastructure, skills and predictability, even strong quarterly results will remain islands of private competence in a sea of public underperformance.
Disclaimer
This article is for informational purposes only and does not constitute investment advice. Past performance is not indicative of future results. Readers should conduct their own research or consult a qualified financial advisor before making any investment decisions.
Official Sources
Company filings and consolidated financial results of FSN E-Commerce Ventures Ltd for the quarter ended 30 September 2026, as reported by NDTV Profit, Inc42, Reuters and CNBC-TV18 on 4 November 2026.
"The decisions we make today will shape the world for generations to come."