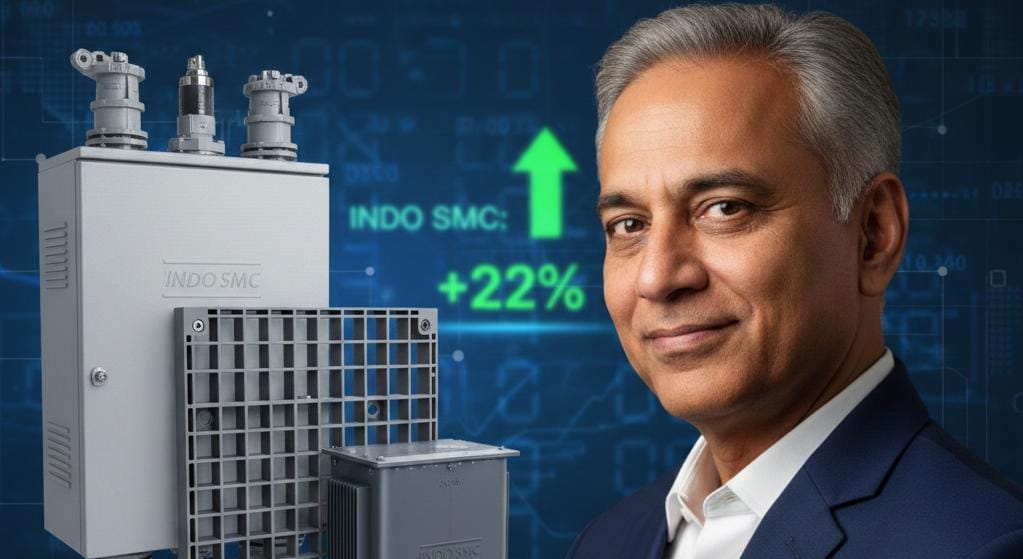
The Indian SME IPO market has kickstarted 2026 with significant momentum, and among the most talked-about entries is Indo SMC Limited. Specializing in the niche but critical sector of composite materials and electrical distribution components, the company is hitting the BSE SME platform with a ₹91.95 crore public issue.
What makes this IPO particularly noteworthy is the backing of "Big Whale" investor Ashish Kacholia, whose participation often serves as a proxy for high-growth potential in the small-cap space. As the subscription window opens from January 13 to January 15, 2026, investors are weighing the company's explosive revenue growth against its aggressive valuation. This article provides a comprehensive 360-degree analysis of Indo SMC’s business model, financial health, and investment potential.
The Company Profile: A Specialist in Composites
Incorporated in September 2021 and headquartered in Ahmedabad, Gujarat, Indo SMC has rapidly carved a niche in the electrical and infrastructure sectors. The company operates across three primary business verticals:
- Sheet Moulding Compound (SMC) Products: Manufacturing energy meter enclosure boxes, SMC sheets, and chequered plates.
- Fiberglass Reinforced Plastic (FRP) Products: Producing industrial gratings and customized molded products.
- Electrical Components: Designing high-tension (HT) and low-tension (LT) current and potential transformers, distribution panels, and feeder pillars.
Indo SMC’s unique selling proposition (USP) lies in its integrated manufacturing model. With four facilities across Gujarat, Maharashtra, and Rajasthan, the company handles everything from in-house mold development and tooling to R&D and testing. This vertical integration allows for faster product development cycles and higher quality control—essential for its role as an approved vendor for various State Electricity Boards (SEBs) and DISCOMs.
IPO Details at a Glance
The Indo SMC IPO is a 100% fresh issue, meaning the entire proceeds will flow back into the company to fuel expansion.
- Investor Reservation: The issue is structured to attract diverse capital, with 47.45% reserved for Qualified Institutional Buyers (QIBs), 33.25% for Retail, and 14.29% for Non-Institutional Investors (NIIs). Notably, the company raised ₹26.16 crore from 17 anchor investors, including HDFC Bank and various focused equity funds, prior to the public opening.
The Financial Trajectory: Explosive Growth
Indo SMC’s financial statements tell a story of rapid scaling. Since its inception in late 2021, the company has seen its revenue grow from a modest ₹7.30 crore in FY23 to a staggering ₹138.78 crore in FY25.
Key Financial Metrics (in ₹ Crores)
- Revenue (FY25): ₹138.78 (vs ₹28.06 in FY24)
- Profit After Tax (FY25): ₹15.44 (vs ₹3.00 in FY24)
- H1-FY26 Revenue: ₹112.62 (indicating another record-breaking year)
- Return on Equity (ROE): 74.45%
- Debt-to-Equity Ratio: 1.00
The company’s order book stood at approximately ₹111.66 crore as of November 30, 2025, providing strong revenue visibility for the upcoming quarters. However, analysts have noted that the "quantum surge" in the bottom line over such a short period (FY24 to FY25) warrants a cautious look at the sustainability of such high margins in a competitive electrical equipment market.
Objects of the Issue
The proceeds of ₹91.95 crore are earmarked for strategic growth:
**₹25.71 Crore: For capital expenditure to purchase new plant and machinery to expand production capacity for SMC and FRP products.
**₹52.00 Crore: To meet incremental working capital requirements, essential for executing the growing order book.
Balance: General corporate purposes and issue expenses.
Strengths vs. Risks
The Bull Case (Strengths)
- Integrated Manufacturing: In-house R&D and tooling reduce dependence on third-party vendors and improve margins.
- Strong Backing: The presence of Ashish Kacholia and reputable anchor investors boosts market confidence.
- Sector Tailwinds: India’s push for "Power for All," smart meter installations, and infrastructure upgrades directly benefits Indo SMC’s product lines.
- High Return Ratios: An ROE of 74.45% and ROCE of 31.39% are exceptionally high for a manufacturing concern.
The Bear Case (Risks)
- Valuation: Based on FY25 earnings, the P/E ratio is approximately 22.04x. If one annualizes the FY26 earnings, the P/E drops to about 14.8x. While competitive, some analysts label it as "aggressively priced."
- High Competition: The company operates in a fragmented market with several established players in the electrical components space.
- Customer Concentration: Being an approved vendor for government utilities is a double-edged sword; while it ensures volume, it can lead to slower payment cycles (working capital intensity).
Market Sentiment and GMP
As of the opening day, the Grey Market Premium (GMP) for Indo SMC was hovering around ₹31 to ₹36, indicating a potential listing gain of roughly 20–24%. This suggests that despite the aggressive pricing, the market is optimistic about the company’s growth story and the "Kacholia factor."
Final Verdict: Should You Invest?
Indo SMC Limited is a classic "high-growth, high-risk" SME play. It has demonstrated an incredible ability to scale revenue and profits within just four years of incorporation. Its involvement in the SMC and FRP sectors places it at the heart of India's infrastructure evolution.
- For Aggressive Investors: The strong order book and marquee investor backing make this an attractive candidate for potential listing gains and long-term participation in the infrastructure theme.
- For Conservative Investors: The SME platform involves higher lot sizes (₹2.98 lakh minimum for retail) and lower liquidity. The rapid jump in profits may also invite scrutiny regarding margin sustainability.
Indo SMC is a "power" player in the making, but like all SME IPOs, it requires a thorough assessment of one's risk appetite.