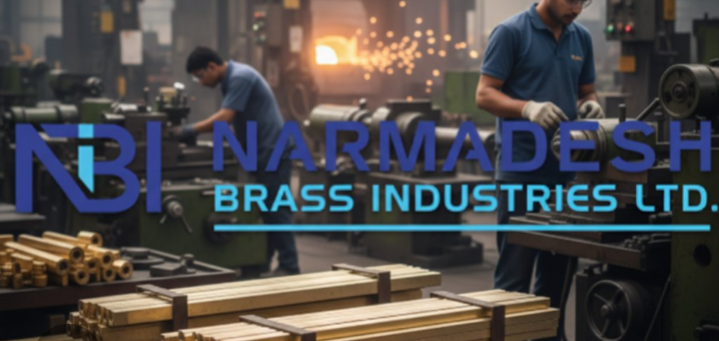
The Indian SME sector is witnessing a robust wave of primary market activity, and the latest entrant to catch the eye of seasoned investors is Jamnagar-based Narmadesh Brass Industries Limited. Opening its subscription on January 12, 2026, this IPO represents a significant milestone for a company that has evolved from a 2019 partnership into a modern, integrated brass manufacturing powerhouse. Situated in the heart of Jamnagar—famously known as India's "Brass City"—Narmadesh Brass Industries is looking to leverage its strategic location and manufacturing excellence to scale new heights.
1. IPO Snapshot: Key Details and Timelines
The Narmadesh Brass Industries IPO is a fixed-price issue aggregating to approximately ₹44.87 crore. This offering is a blend of a fresh issue to pump capital into the business and an offer for sale (OFS) providing an exit/liquidity to existing stakeholders.
Investors should note the entry barrier; the minimum investment for a retail participant stands at ₹2,47,200 (2 lots/480 shares), while High Net-worth Individuals (HNIs) are looking at a minimum commitment of ₹3,70,800.
2. Business Overview: From Billets to Branded Valves
Narmadesh Brass Industries isn't just a simple component maker; it operates across the entire brass value chain. Spanning a manufacturing facility of 6,293 sq. meters, the company has built an integrated ecosystem where raw materials are transformed into high-precision engineering products.
The Product Portfolio
- Core Semi-Finished Goods: Brass Billets and Extruded Rods (with a massive 4,320 MT per annum capacity).
- Plumbing & Sanitary: Lead-free fittings and high-grade valves sold under their own brand.
- Specialized Components: Agricultural sprayer parts, garden fittings, and customized CNC/VMC machined components.
- Services: In-house casting, forging, and turning services that provide a "one-stop-shop" experience for global and domestic B2B clients.
- Strategic Moat: One of the company’s unique selling propositions is its ability to manufacture brass rods of size above 3 inches in lengths exceeding 2 meters—a feat few competitors in the Jamnagar cluster can match.
3. Financial Health: Analyzing the Numbers
The financial trajectory of Narmadesh Brass Industries shows a company in a high-growth phase, albeit with some of the typical growing pains associated with capital-intensive industries.
- Revenue Growth: The company’s revenue from operations has seen a steady climb from ₹59.96 crore in FY23 to ₹87.72 crore in FY25.
- Profitability Trends: While the top line is growing, the bottom line (PAT) has shown some volatility. In FY25, PAT stood at ₹5.72 crore, a dip from the ₹7.10 crore recorded in FY24. However, the first half of FY26 (ending Sept 2025) has already seen a PAT of ₹4.01 crore, suggesting a potential recovery and improved margin management.
- Key Ratios: The company boasts a healthy Return on Equity (ROE) of 49.99% for FY25 and a Price-to-Earnings (P/E) ratio of approximately 19.6x - 19.9x post-issue.
4. Objectives of the Issue: Where is the Money Going?
Transparency in the "Use of Proceeds" is a key indicator of management's focus. Narmadesh Brass has clearly outlined four primary areas for the ₹36.09 crore raised via the fresh issue:
- Debt Reduction (₹14.50 Cr): Repayment or prepayment of outstanding borrowings to strengthen the balance sheet and reduce interest costs.
- Working Capital (₹10.20 Cr): As a high-volume manufacturing business, maintaining liquidity for raw material procurement (Copper, Zinc, Scrap) is vital.
- Capital Expenditure (₹3.29 Cr): Purchase of new machinery and equipment to further automate and expand production lines.
- General Corporate Purposes (₹4.60 Cr): Brand building and operational contingencies.
5. Investment Thesis: Strengths vs. Risks
The Strengths
- Integrated Infrastructure: In-house R&D, tool rooms, and an extrusion plant allow for strict quality control and better margins compared to outsourced models.
- Location Advantage: Being in Jamnagar reduces logistics costs and ensures a steady supply of skilled labor and raw materials.
- Promoter Expertise: Led by Mr. Hitesh Dudhagara, a mechanical engineer with 20+ years of experience, the company is managed by industry veterans who understand the technical nuances of metallurgy.
The Risks
- Raw Material Volatility: Brass prices are directly linked to global Copper and Zinc markets. Any sudden spike can squeeze margins.
- Client Concentration: A significant portion of revenue is derived from the top 10 customers.
- Small Equity Base: As an SME listing, the stock may face lower liquidity compared to mainboard stocks, leading to higher price volatility.
6. The Verdict
Narmadesh Brass Industries presents an interesting opportunity for investors seeking exposure to India's "Make in India" manufacturing story. While the Grey Market Premium (GMP) has been muted at the start, indicating a flat listing, the company's strong asset base and strategic expansion plans offer long-term value.
At a P/E of roughly 20x, the issue is priced competitively compared to peers like Poojawestern Metaliks and Siyaram Recycling, though it is not "cheap" by SME standards. Investors with a medium-to-long-term horizon who believe in the recovery of the industrial hardware and plumbing sectors may find this an attractive addition to their portfolios.